
We strive to help keep you up to date with key changes
Browse our blog or download resources to better understand your tax affairs
Cryptoassets: Are you reporting correctly?
Cryptoassets – which include cryptocurrency – are big business. In 2025, around 741 million people owned cryptocurrency globally, with Bitcoin and Ethereum remaining the poster children of the industry…
The 2026 Tax Time Toolkit: how it helps your small business
The Australian Taxation Office (ATO) has released its Tax Time toolkit for small business for the 2026 filing season, which covers the period 1 July 2025 to 30 June 2026. What’s inside the toolkit?…
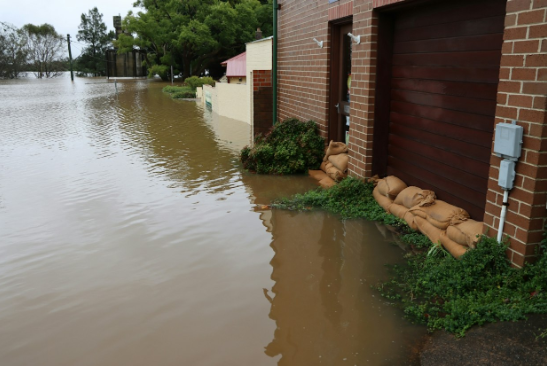
Managing risk: Protecting your business against emergency weather conditions
Managing and mitigating risk is one of your key responsibilities as a business owner. And in recent years, we’ve seen an increasing level of risk associated with extreme environmental conditions and fluctuating weather events…
OCTOBER EDITION | CLIENT NEWSLETTER
Welcome to the October edition of our client newsletter. This month, we’ve complied a selection of timely and practical insights across tax, superannuation and financial planning - helping you stay informed, confident, and in control of your financial decisions.
In this edition:
AI AND QUALITY DATA: A Powerful Tool for the Tax Office: The ATO is increasingly using artificial intelligence and advanced data matching to identify undeclared income, incorrect deductions, and tax reporting discrepancies. Combined with extensive data sources, including passenger movement records, the ATO's ability to detect non-compliance is stronger than ever. Taxpayers should ensure their records and claims are accurate and up to date.
Do you need to get a market value of your home at 30 June 2027?: With the 50% CGT discount set to be replaced by an inflation-based indexation method from 1 July 2027, property owners may need a market valuation as at 30 June 2027. This is particularly important if your home has been used to produce income, such as through renting rooms, operating a business from home, or other partial CGT exemption situations.
Determining a person’s residence for tax purpose is not an easy matter!: A recent Federal Court case highlights that simply working overseas does not necessarily end your Australian tax residency. Strong ties to Australia, including family, assets, and regular visits, can result in continued Australian tax obligations on worldwide income. If you're relocating overseas or returning to Australia, it's important to understand your residency status.
BRINGING YOUR OVERSEAS RETIREMENT SAVINGS HOME: If you have retirement savings in a foreign superannuation fund, transferring them to Australia can offer benefits, but timing is critical. Transfers within six months of becoming an Australian tax resident may avoid additional tax, while later transfers can trigger tax on investment growth. Professional advice is essential before making a move.
SUPER AND MORTGAGE ARREARS: What the rules already allow: Did you know you may be able to access your super on compassionate grounds if you're at risk of losing your home? Eligible homeowners can apply to withdraw funds to cover mortgage arrears, council rates, or certain debts threatening the sale of their principal residence. Strict conditions apply, and early withdrawals can significantly impact retirement savings.
Government moves to tighten protections in super: Following recent super fund collapses, the Government has proposed stronger protections for retirement savings. Changes may include caps on advice fees deducted from super accounts, significantly higher penalties for trustee breaches, expanded ASIC enforcement powers, and additional requirements for SMSF trustees. These reforms are still subject to legislation.